

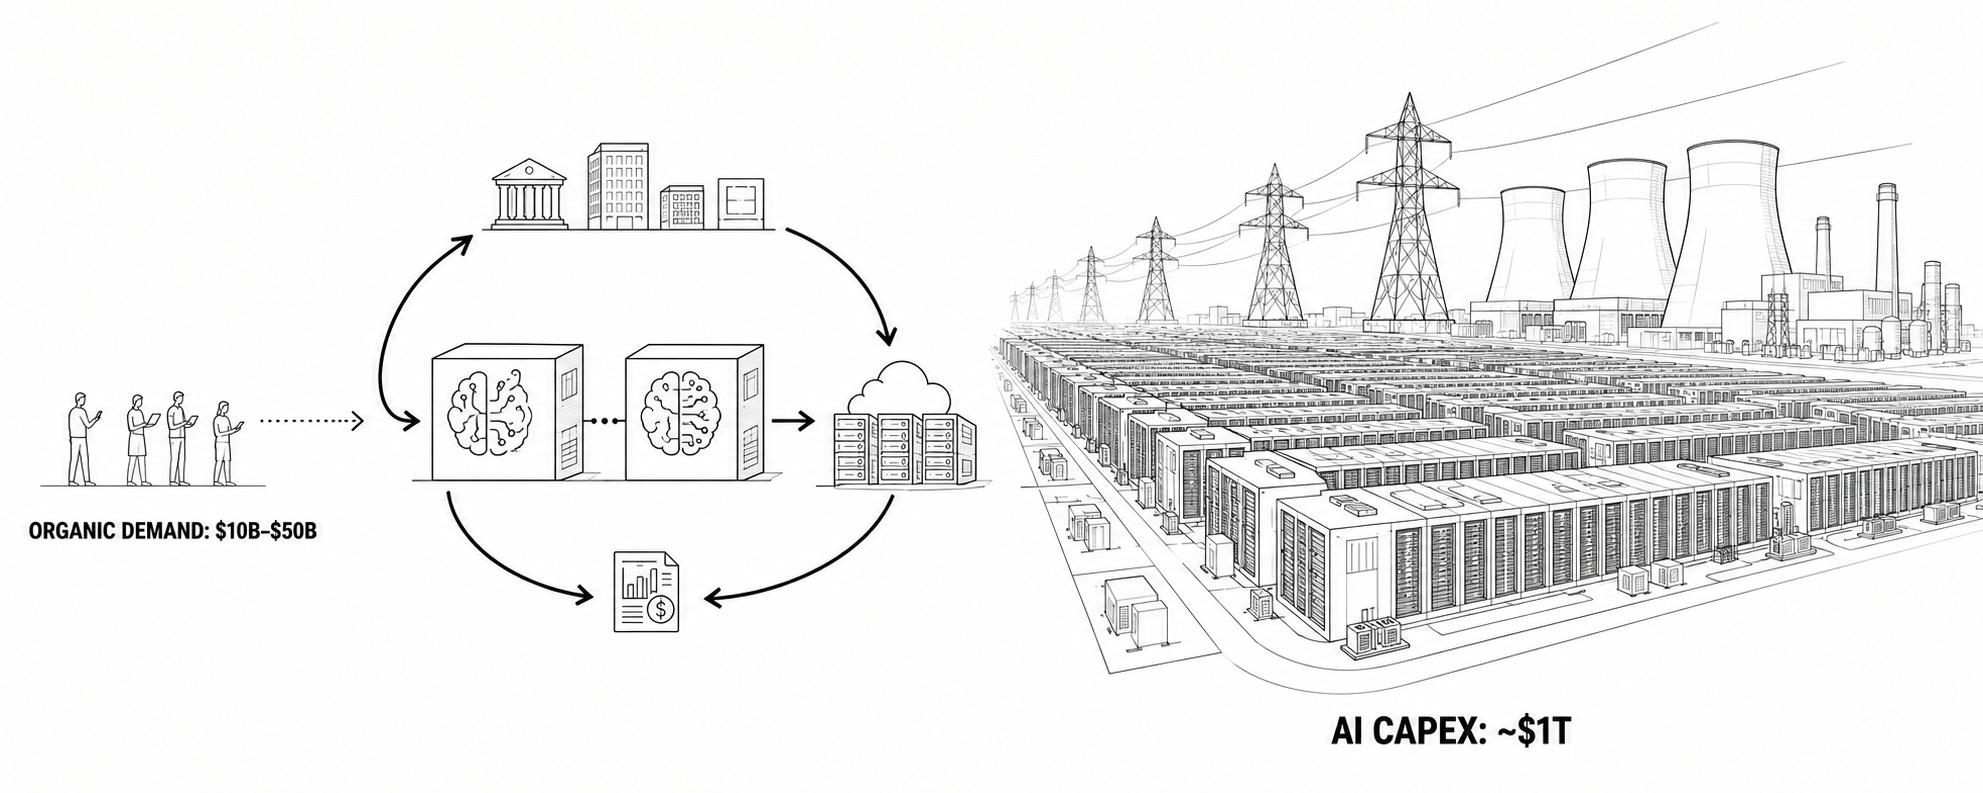
GPT analysis of my earlier post. Orders of magnitude: organic “real” demand for AI versus Capex and future cash flows.
The central claim in Hsu’s original X post is supported by the available evidence: current AI revenue is heavily concentrated in OpenAI and Anthropic, while much of those companies’ spending is financed by investors rather than by operating profits. The amount of genuinely organic demand—money ultimately coming from consumers and established, cash-generating companies—appears to be only of order $10 billion. A more detailed reconstruction might produce $30–50 billion rather than exactly $10 billion, but these are consistent order-of-magnitude estimates. Either is tiny compared with the hundreds of billions being invested annually in AI infrastructure.
The concentration claim is best documented at Microsoft. Its FY2026 filing reports $24.1 billion of revenue from OpenAI, including revenue-sharing payments, against analyst estimates of roughly $34.5 billion in total Microsoft AI revenue. That implies approximately 70% dependence on OpenAI. Microsoft also reported $6 billion of OpenAI accounts receivable at year-end.
For AWS, analyst estimates put OpenAI and Anthropic at roughly 59–73% of AI revenue, although Amazon does not disclose customer concentration. Amazon has said its AI business now exceeds a $25 billion annual revenue run rate, while Anthropic has committed more than $100 billion to AWS over ten years.
Amazon Q2 results, Anthropic–AWS agreement
Google is less transparent. UBS estimates reportedly imply that OpenAI and Anthropic constitute about 28% of total Google Cloud revenue in 2026 and nearly half in 2027. Because Google Cloud also includes conventional computing, storage and software, the two labs could plausibly represent most of its specifically AI-related revenue, but the “70%” figure is inferred rather than disclosed. Google Cloud revenue nevertheless grew 82% in Q2, driven primarily by AI infrastructure and enterprise AI services.
The crucial point is that revenue at successive layers of the AI stack cannot be added together as independent demand. A company may pay Anthropic for Claude usage; Anthropic then pays AWS or Google for the compute. The same external dollar appears first as model-company revenue and again as cloud revenue. Moreover, when Anthropic or OpenAI spends more on compute than it receives from customers, the difference is supplied by newly raised capital. OpenAI, for example, reports about $2 billion in monthly revenue but raised $122 billion at an $852 billion valuation in March. Anthropic reports a $47 billion revenue run rate but simultaneously raised $65 billion at a $965 billion valuation.
OpenAI funding disclosure, Anthropic Series H
After removing double counting and heavily discounting AI consumption by loss-making, venture-funded startups, a reasonable estimate of current final demand is approximately:
$15–20 billion from OpenAI consumers and established enterprises;
$10–20 billion from Anthropic consumers and established enterprises;
perhaps another $5–10 billion from other direct products and non-lab enterprise AI consumption.
That gives roughly $30–50 billion of annualized organic demand. But this remains of order ~$10B, precisely the scale asserted in the original post. Indeed, given the uncertainty surrounding Anthropic’s rapidly annualized “run-rate” metric and the startup share of enterprise API consumption, $10 billion is a defensible lower-end estimate. Reuters has noted the striking gap between Anthropic’s claimed annualized run rate and the much smaller amount of revenue it had actually booked cumulatively.
Against this ~$10B organic revenue base, the infrastructure buildout is ~$trillion. Amazon, Microsoft, Alphabet and Meta are on course to spend roughly $700 billion in 2026, with Oracle and other providers pushing the total higher. Not all of this is AI-related, but approximately $450–600 billion probably is.
The spending is already consuming most of the hyperscalers’ cash generation. Amazon’s trailing free cash flow was negative $7.6 billion; Meta produced only $784 million of Q2 free cash flow after $31.1 billion of capex; and Alphabet reported negative $5.9 billion of Q2 free cash flow. Microsoft remains strongly cash-generative, but its cash capex nearly doubled to $115.9 billion, with another $24.6 billion of infrastructure obtained through finance leases. Current net income figures are also flattered by paper gains: Amazon’s Q2 earnings included a $53.4 billion pre-tax gain primarily on Anthropic, while Alphabet recorded a $77.1 billion after-tax gain on equity securities.
A simple capital-recovery calculation illustrates the hurdle. If the industry invests $450–550 billion annually in AI infrastructure from 2026 through 2029, it will create roughly $1.8–2.2 trillion of installed capital. Assuming a five-year blended economic life, a 9% required return and 40–60% cash contribution margins, that infrastructure ultimately needs approximately $700 billion to $1.3 trillion of annual revenue. A central estimate is about $1 trillion.
Growing an organic base of $30–50 billion to $700 billion–$1.1 trillion by 2030 requires approximately 90–120% annual growth. In other words, organic AI spending must roughly double every year for another four years. The private valuations of OpenAI and Anthropic alone require somewhat less but still extraordinary growth: their combined $1.8 trillion valuation plausibly requires $300–500 billion of annual revenue by 2030, implying roughly 60–90% annual organic growth from the estimated present base.
Thus, the more detailed analysis reinforces the original post. Whether present organic AI revenue is labeled $10 billion, $30 billion or even $50 billion does not materially change the conclusion. The industry is attempting to support an ~$trillion capital base with an ~$10B final-demand base. The capex and current valuations can make sense—but only if organic use approximately doubles every year, customer concentration falls, and margins improve despite rapidly declining compute prices.
If organic demand grows at a still-impressive 50% annually, a $40 billion base reaches only about $200 billion by 2030. That would support several very valuable AI businesses, but not the infrastructure currently being built. In that scenario, the likely outcome is substantial excess capacity, collapsing compute prices, asset impairments and valuation compression—especially for model labs, Nvidia, neoclouds and leveraged data-center projects.
i think the depreciation actually is longer. a100 chips are still in use. the architecture of a built center precludes slotting in new chips - different cooling requirements, different power, and so on. so that center will be used as long as its product is worth more than the cost of compute. also the projected queue of centers is stretching out and thinning because of a variety of impediments - permitting/siting, transformers and turbines on a 3-4 year waiting list, cost of capital rising, and so on.
Steve do you read semi-analysis? They just put out a piece on SpaceX and draw the complete opposite conclusion. They see lab token profit margins at ~85%. I am not saying they are right and you are wrong but I would recommend reading the bull case.